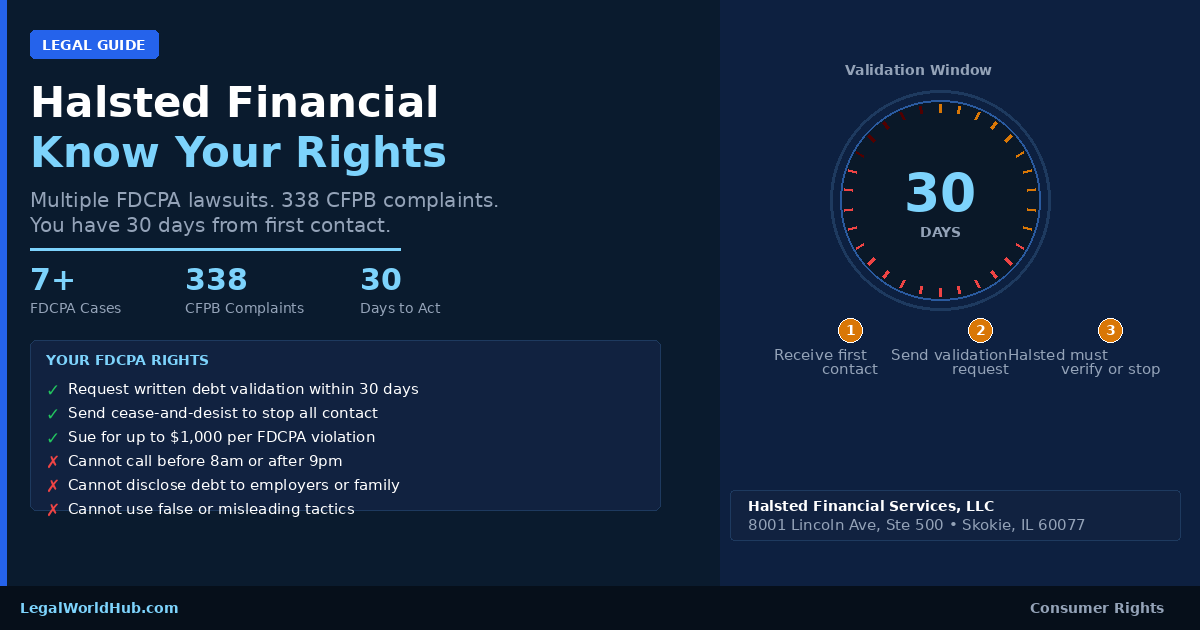
Halsted Financial Services has been sued under the Fair Debt Collection Practices Act multiple times across federal courts in New York, New Jersey, Illinois, and Oklahoma. The company has 338 CFPB complaints. If Halsted contacts you, you have specific legal rights and a 30-day window to protect them.
What Is Halsted Financial Services?
Halsted Financial Services, LLC is a third-party debt collection agency headquartered at 8001 Lincoln Ave, Suite 500, Skokie, Illinois 60077. The company has been in business since May 2008.
Halsted collects several types of consumer debt, including:
- Healthcare and medical debt
- Credit card debt
- Payday loan debt
As a third-party debt collector, Halsted is fully subject to the Fair Debt Collection Practices Act (FDCPA), 15 U.S.C. § 1692. This means every communication it sends you, calls, letters, texts, and emails, must comply with federal law.
Halsted Financial Services Lawsuits
Consumers have filed multiple FDCPA lawsuits against Halsted across several federal courts. No court has issued a major merits ruling finding Halsted liable for systemic violations. Most cases were dismissed on procedural or standing grounds before reaching a verdict.
Key Halsted Financial Services Cases
| Case | Court | Year | Outcome |
|---|---|---|---|
| Warren v. Halsted Financial Services | New York State Court | 2025 | Dismissed — standing |
| Jones v. Halsted (5:2023cv01175) | W.D. Oklahoma | 2024 | Dismissed Aug 2024 |
| Pistone v. Halsted | D. New Jersey (Judge Shipp) | 2022 | Dismissed Mar 2022 |
| Tukin v. Halsted (21-cv-00025) | N.D. Illinois | 2021 | Dismissed 2021 |
| Benhayun v. Halsted (2:21-cv-04421) | E.D. New York | 2021 | Outcome unconfirmed |
| Razilova v. Halsted (1:18-cv-01668) | E.D. New York | 2018 | Class action – outcome unconfirmed |
| Coleman v. Halsted et al. (1:18cv5323) | N.D. Illinois | 2018 | Class action vs Halsted + National Credit Adjusters |
What the Lawsuits Alleged
The FDCPA lawsuits against Halsted Financial Services share a common pattern of allegations:
False or misleading debt payment deadlines. The ClassAction.org-covered case alleged Halsted sent collection letters that stated a specific deadline for payment that created a false sense of urgency. Under FDCPA Section 1692e, debt collectors cannot use false, deceptive, or misleading representations to pressure payment.
Failure to properly validate debts. Multiple cases alleged Halsted failed to provide adequate written verification of debt amounts, original creditor names, or consumer dispute rights, all required disclosures under FDCPA Section 1692g.
Continued collection without validation. Several cases alleged Halsted continued collection activity after a consumer requested debt validation, which the FDCPA prohibits until verification is provided.
The Zombie Debt Problem: Is Your Halsted Debt Time-Barred?
Zombie debt is the informal name for debt that is past the statute of limitations, the legal window during which a creditor can sue you and win. Once that window closes, Halsted cannot get a court judgment against you, even if the debt is real and unpaid.
The statute of limitations on debt varies by state and by debt type. Common windows:
- California: 4 years from the date of last payment
- New York: 3 years
- Texas: 4 years
- Florida: 5 years
- Illinois: 5 years
- New Jersey: 6 years
- Pennsylvania: 4 years
Two things to know before responding to Halsted:
First, making any payment, even a partial one, can restart the statute of limitations clock in many states. Do not pay anything on an old debt until you know whether the limitations period has expired.
Second, even if the debt is time-barred, Halsted can still attempt to collect voluntarily. They simply cannot win a lawsuit to force you to pay. If they file a lawsuit on a time-barred debt, that may itself be an FDCPA violation.
Is There an Open Halsted Financial Services Settlement?
No. There is no open consumer class action settlement against Halsted Financial Services as of September 2026. No CFPB enforcement action, FTC consent order, or state AG settlement has been filed against Halsted.
If a new settlement opens in the future, claim deadlines typically run 60 to 180 days from the settlement notice date. You can monitor open class action settlements for new cases.
Your FDCPA Rights Against Halsted Financial Services
The Fair Debt Collection Practices Act gives you specific, time-sensitive rights the moment Halsted contacts you.
The 30-Day Validation Window, Your Most Important Right
Within 5 days of Halsted’s first contact, they must send you a written notice including:
- The amount of the debt
- The name of the original creditor
- A statement of your right to dispute the debt within 30 days
If you dispute the debt in writing within 30 days, Halsted must stop all collection activity until it sends you written verification of the debt. Missing this 30-day window weakens your position significantly.
Send your dispute letter by certified mail, return receipt requested. Keep the receipt.
The Right to Stop All Contact
You can send Halsted a written cease-and-desist letter demanding all contact stop. Under FDCPA Section 1692c(c), once Halsted receives it, the company may only contact you to:
- Confirm it will stop
- Notify you of a specific legal action (like a lawsuit)
Any other contact after a written cease-and-desist is an FDCPA violation.
What Halsted Cannot Do
Under the FDCPA, Halsted Financial Services cannot:
- Call you before 8 a.m. or after 9 p.m. in your local time zone
- Call you repeatedly to harass or annoy you
- Use profane or abusive language
- Threaten legal action it does not intend to take
- Disclose your debt to your employer, neighbors, or family members
- Misrepresent the amount you owe
- Use false or misleading collection tactics
Your Right to Sue
If Halsted violates the FDCPA, you can file a lawsuit in federal court within one year of the violation. Successful plaintiffs may recover:
- Up to $1,000 in statutory damages
- Actual damages for financial harm
- Attorney fees — many consumer rights attorneys handle FDCPA cases on contingency
How to Handle a Halsted Financial Services Debt
Step 1: Do not pay or acknowledge the debt on the first call. Payment or verbal acknowledgment can restart the statute of limitations on old debts in some states.
Step 2: Request debt validation in writing. Mail a debt validation letter within 30 days of first contact. Request the original creditor name, account number, amount breakdown, and proof Halsted has the legal right to collect.
Step 3: Verify the debt is yours. Check your own records and your free credit reports at annualcreditreport.com to confirm the account.
Step 4: Check the statute of limitations. Most states give creditors 3 to 6 years to sue on a credit card or medical debt. If the debt is older than your state’s limit, Halsted cannot win a lawsuit to collect though it can still try to collect voluntarily.
Step 5: Document every contact. Log the date, time, phone number, and what was said in every call. Save every letter. This record is essential if you need to file a complaint or lawsuit.
Step 6: File complaints if your rights are violated. Report violations to the CFPB at ConsumerFinance.gov and to the FTC at reportfraud.ftc.gov.
Sample Debt Validation Letter for Halsted Financial Services
Use this template when responding in writing within 30 days of first contact:
[Your Name] [Your Address] [Date]
Halsted Financial Services, LLC 8001 Lincoln Ave, Suite 500 Skokie, IL 60077
Re: Account Number [Account Number from Halsted’s letter]
To Whom It May Concern:
I am writing in response to your collection notice dated [date]. I dispute this debt and request written verification per my rights under the Fair Debt Collection Practices Act, 15 U.S.C. § 1692g.
Please provide:
- The name and address of the original creditor
- The original account number
- A complete breakdown of the amount claimed, including principal, interest, and fees
- Proof that your company has the legal right to collect this debt
- A copy of the original signed credit agreement
Until you provide this verification, please cease all collection activity as required by 15 U.S.C. § 1692g(b).
Sincerely, [Your Name]
Send by certified mail, return receipt requested. Keep a copy and the tracking receipt.
Frequently Asked Questions About Halsted Financial Services
Is Halsted Financial Services a legitimate debt collector?
Yes. Halsted Financial Services LLC is a licensed, operating debt collection agency based in Skokie, Illinois. It is not a scam. However, it has faced multiple FDCPA lawsuits and has 338 complaints with the CFPB. Verify any debt independently before paying.
Why is Halsted Financial Services calling me?
Halsted is contacting you because a creditor hired it to collect a debt they believe you owe, most commonly a medical bill, credit card balance, or payday loan. Always request written validation of the debt before taking any action.
How do I get Halsted Financial Services to stop calling?
Send a written cease-and-desist letter by certified mail to Halsted’s address at 8001 Lincoln Ave, Suite 500, Skokie, IL 60077. Once received, Halsted can only contact you to confirm it will stop or to notify you of a lawsuit. Calls after that letter is received are FDCPA violations.
Can Halsted Financial Services sue me?
Yes, Halsted can file a lawsuit to collect a debt. If you are served with a lawsuit, you must respond by the court deadline or a default judgment will be entered against you. Check whether the debt is within your state’s statute of limitations, if it is past that limit, that is a defense you can raise in court.
What is the statute of limitations on Halsted debt collection?
The statute of limitations depends on your state and the type of debt. Most states set it between 3 and 6 years from the date of last payment or last activity. After that period, Halsted cannot win a court judgment to force payment, though it may still attempt to collect voluntarily. Check your state’s specific rules before responding to old debts.
How do I dispute a Halsted Financial Services debt?
Send a written dispute and debt validation request within 30 days of Halsted’s first written contact. Use certified mail, return receipt requested. Halsted must stop collection activity until it provides written verification of the debt. See the sample letter above for the full template.
Has Halsted Financial Services been sued?
Yes. Consumers have filed FDCPA lawsuits against Halsted in federal courts in New York, New Jersey, Illinois, and Oklahoma between 2014 and 2025. Most cases were dismissed on procedural grounds before reaching a full trial. No major class action settlement has been reached.
Where do I report Halsted Financial Services violations?
File complaints with the CFPB at ConsumerFinance.gov/complaint and with the FTC at reportfraud.ftc.gov. If Halsted violated the FDCPA, consult a consumer rights attorney — attorney fees are recoverable if you win an FDCPA case.
This article is for informational purposes only and does not constitute legal advice. If Halsted Financial Services has violated your rights, consult a licensed consumer rights attorney in your state.
Sources: CourtListener federal case records; CFPB Consumer Complaint Database; BBB business profile for Halsted Financial Services LLC; FDCPA 15 U.S.C. § 1692 (full text at law.cornell.edu).
Related: Open Class Action Settlements You Can File Today | Transworld Systems: Debt Collector Rights Guide