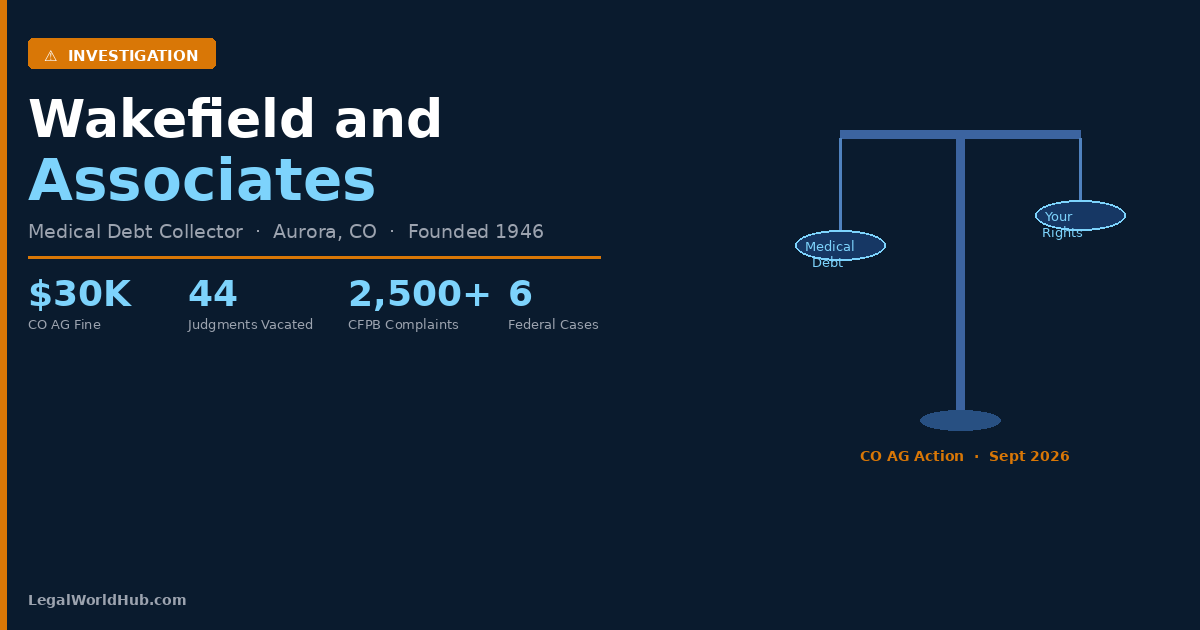
Five days ago, the Colorado Attorney General announced a settlement against Wakefield and Associates for illegally obtaining court judgments against 44 consumers without filing required legal documents. All 44 judgments were vacated. Multiple federal courts have also found Wakefield charged unauthorized interest on medical debt. Here is what that means if Wakefield is contacting you now.
What Is Wakefield and Associates?
Wakefield and Associates, Inc. is a medical debt collection company founded in 1946 and headquartered at 10800 E. Bethany Dr., Suite 450, Aurora, Colorado. The company specializes almost exclusively in collecting medical debt on behalf of:
- Hospitals and health systems
- Emergency room physician groups
- Air medical transport services (including Air Evac)
- Dental offices
Wakefield operates as both a collection agency (collecting on behalf of healthcare providers) and a debt buyer (purchasing charged-off medical accounts outright). Because they collect consumer debt, they are fully subject to the Fair Debt Collection Practices Act.
Their consumer dispute address is: Wakefield and Associates, Inc., c/o Compliance Team, Department #888640, Knoxville, TN 37995.
Colorado AG Settlement – September 23, 2026
Colorado Attorney General Phil Weiser announced a settlement against Wakefield and Associates on September 23, 2026, five days before publication of this article.
The AG found Wakefield violated Colorado’s 2023 Medical Debt Protection Law (Senate Bill 23-093) by:
- Obtaining court default judgments against 44 consumers without filing legally required affidavits
- Failing to submit documentation required under Colorado law before obtaining those judgments
- Securing court orders to collect debts without the evidentiary foundation the law demands
What the settlement required:
- Wakefield paid a $30,000 civil fine
- All 44 court judgments against Colorado consumers were vacated, meaning those consumers’ judgments no longer exist
- This is the first enforcement action brought under Colorado’s 2023 medical debt protection statute
If Wakefield obtained a judgment against you in Colorado, you may be among the 44 consumers whose judgment was vacated. Contact the Colorado AG’s office for confirmation.
Wakefield and Associates FDCPA Lawsuits
Federal courts have seen multiple FDCPA lawsuits against Wakefield. The recurring pattern across these cases is unauthorized interest charged on medical debts.
Wakefield and Associates Lawsuit Summary Table
| Case | Case No. | Court | Year | Allegation |
|---|---|---|---|---|
| Hernandez v. Wakefield | 8:24-cv-00897 | M.D. Florida | 2024 | Unauthorized interest on medical debt |
| Trim v. Wakefield | 3:20-cv-02420 | S.D. California | 2020 | Covert recording of medical debt calls |
| Haskell v. Wakefield | 20200412-CA | Utah Court of Appeals | 2021 | Unlicensed collection in Utah |
| Baker v. Wakefield | 4:18-cv-00473 | E.D. Arkansas | 2018 | Unauthorized interest (Air Evac accounts) |
| Velez v. Wakefield | 1:18-cv-20453 | S.D. Florida | 2018 | Interest not disclosed in collection letter |
| Machnik v. Wakefield | 2:18-cv-00678 | E.D. Wisconsin | 2018 | Failed to identify current creditor |
The Unauthorized Interest Pattern
The most consistent allegation across Wakefield cases is that Wakefield added interest to medical debt balances without legal authority to do so.
Under the FDCPA, a debt collector can only collect interest if the original contract or applicable state law permits it. Medical billing contracts rarely include interest provisions. Adding unauthorized interest violates FDCPA Section 1692f(1), which prohibits collecting amounts not expressly authorized by the agreement or law.
What to check on your Wakefield notice: If your collection letter shows an amount higher than the original medical bill, look for a line showing interest or fees. Request written documentation of the legal basis for any interest charged. If Wakefield cannot provide it, that is a potential FDCPA violation.
The Hernandez Settlement (Closed, April 2025)
The Hernandez v. Wakefield case (8:24-cv-00897, M.D. Florida) resulted in an $87,500 class action settlement. The claim deadline was April 29, 2025, and payments were distributed on July 21, 2025. That settlement is fully closed. It is documented here as a recent example of confirmed FDCPA conduct, not as an open claim opportunity.
Medical Debt and Your Credit Report
In 2024 and early 2025, the CFPB proposed a rule to ban medical debt from consumer credit reports. A federal court struck down that rule in July 2025. Wakefield can still report unpaid medical accounts to Equifax, Experian, and TransUnion.
However, 12 states have their own bans on medical debt credit reporting, including Colorado, California, New York, and others. If you live in one of those states, Wakefield may not lawfully report your medical debt to credit bureaus regardless of the federal rule.
Check your state’s current medical debt reporting rules if Wakefield has placed or threatened to place a collection entry on your credit report.
Your FDCPA Rights Against Wakefield and Associates
Right to Written Debt Validation
Within 5 days of first contact, Wakefield must send you a written notice stating:
- The amount of the debt
- The name of the original creditor (the hospital, physician group, or transport service)
- Your right to dispute the debt within 30 days
Send your dispute and validation request within 30 days by certified mail to: Wakefield and Associates, Inc., c/o Compliance Team, Department #888640, Knoxville, TN 37995.
Right to Dispute Unauthorized Interest
If Wakefield’s letter shows any amount above your original medical bill, request in writing the specific contractual provision or state statute that authorizes them to collect that interest or fee. If they cannot provide it, document that response and consult a consumer rights attorney.
Right to Stop Contact
A written cease-and-desist letter stops all Wakefield collection calls. They may only contact you after that to confirm they will stop or to notify you of a specific legal action. Any other contact is an FDCPA violation.
Right to Sue
If Wakefield violates the FDCPA, you can file a federal lawsuit within one year of the violation. You may recover up to $1,000 in statutory damages, actual damages, and attorney fees. Many consumer rights attorneys take FDCPA cases on contingency.
How to Dispute a Wakefield and Associates Medical Debt
Step 1: Request the original itemized medical bill. Ask for a complete itemized statement from the original healthcare provider. Compare it to the amount Wakefield claims you owe.
Step 2: Request debt validation. Mail a written request within 30 days of first contact asking for the original creditor’s name, account number, and a breakdown of principal versus interest versus fees.
Step 3: Challenge any interest. If the Wakefield amount exceeds your original bill, ask in writing for the legal basis for any added interest. Courts have found this is a recurring Wakefield violation.
Step 4: Check Colorado medical debt protections. If you are in Colorado, the 2023 Medical Debt Protection Law gives you additional rights. The AG’s September 2026 enforcement action shows those protections are actively enforced.
Step 5: File complaints. Report any violations to the CFPB and the Colorado AG (if in Colorado) at coag.gov.
Frequently Asked Questions About Wakefield and Associates
Is Wakefield and Associates a legitimate debt collector?
Yes. Wakefield and Associates is a licensed medical debt collection company founded in 1946. They are not a scam. However, Colorado’s AG sued them in September 2026 for illegal collection practices, multiple federal courts have found FDCPA violations in their collection letters, and they have over 2,500 CFPB complaints.
Why is Wakefield and Associates calling me?
Wakefield is contacting you to collect an unpaid medical bill. They collect on behalf of hospitals, emergency room physicians, air ambulance services, and dental offices. Always request a written debt validation notice before paying.
Did Colorado sue Wakefield and Associates?
Yes. Colorado Attorney General Phil Weiser announced a settlement with Wakefield on September 23, 2026. Wakefield paid a $30,000 fine after the AG found it obtained court judgments against 44 consumers without filing legally required affidavits. All 44 judgments were vacated under the settlement.
Is there an open Wakefield and Associates settlement I can claim?
No active consumer settlement claim form is currently open. The Hernandez v. Wakefield settlement ($87,500) closed on April 29, 2025. The Colorado AG action resulted in judgment vacaturs and a fine to the state, not a consumer claim fund. Monitor open class action settlements for future cases.
Can Wakefield and Associates add interest to my medical bill?
Only if the original contract with your healthcare provider authorizes it, or if state law permits it. Multiple federal courts have found Wakefield charged interest without legal authority. If your Wakefield letter shows a higher amount than your original bill, request written documentation of the legal basis for any added interest.
How do I get Wakefield and Associates to stop calling me?
Send a written cease-and-desist letter by certified mail to: Wakefield and Associates, Inc., c/o Compliance Team, Department #888640, Knoxville, TN 37995. Once they receive it, they can only contact you to confirm they will stop or to notify you of a lawsuit. All other contact after that is an FDCPA violation.
Can Wakefield and Associates put medical debt on my credit report?
Yes, in most states. A federal rule banning medical debt from credit reports was struck down in July 2025. However, 12 states including Colorado and California have their own medical debt credit reporting bans. Check your state’s current law before assuming Wakefield can or cannot report your account.
What is the phone number for Wakefield and Associates?
Wakefield and Associates contacts consumers from (800) 586-0286. If you receive calls from this number, it is Wakefield. Do not confirm personal or financial information over the phone. Request all communications in writing.
This article is for informational purposes only and does not constitute legal advice. Case and enforcement information reflects publicly available records as of September 2026.
Sources: Colorado AG Press Release, September 23, 2026 (coag.gov); CourtListener federal dockets; CFPB Consumer Complaint Database; FDCPA 15 U.S.C. § 1692; Colorado SB23-093 (Medical Debt Protection Act).
Related: Halsted Financial Services: FDCPA Rights Guide | Transworld Systems: Know Your Rights | Open Class Action Settlements